• 0

Category: High Debt

Should I Use My Side Hustle Money to Pay Off Debt?

Should I Use My Side Hustle Money to Pay Off Debt?

Making extra money sounds amazing until it actually hits your account and somehow just disappears into your regular life. I’ve made money outside of my regular paycheck in a bunch of different ways over the years, some worth it, some honestly not worth the time I put in. But now that I’m trying to aggressively pay off debt, I’ve been thinking a lot more about what I actually want that extra money to do.

If I make an extra $100, $300, or $500 this month, should all of it go toward debt? Should I keep some for myself? And does an extra $100 even move the needle when the debt number is this big? That’s what I wanted to actually sit down and figure out.

Should All of My Side Hustle Money Go Toward Debt?

My first instinct is always yes, obviously, throw all of it at the debt and keep it moving. But real life doesn’t really work that clean.

First I have to figure out how much of that money is even mine to spend. Depending on where it came from, I might need to set some aside for taxes, or there might be expenses tied to whatever I did to make it in the first place. I don’t want to get so excited about sending an extra $500 to a credit card that I end up creating a whole new problem for myself later.

After that it really comes down to what I decided the side hustle was for in the first place. Right now one of my biggest goals is getting rid of debt, so yeah, I want a good chunk of extra money going toward that. But I also don’t buy into the idea that every single dollar I make has to immediately vanish into a credit card payment. If I worked for it and want to keep a little for myself, I can do that.

Maybe I decide 80% goes to debt and I keep 20%. Maybe some months I send all of it. Maybe part of it needs to go back into whatever made me the money in the first place. What I don’t want is to make an extra $300, let it just sit in my checking account with no plan, and then two weeks later have no idea where the hell it went. That’s the part I’m actually trying to change.

How Much Side Hustle Income Should Go Toward Debt?

Honestly I don’t think there’s one percentage that works for everybody. If the money has expenses attached, those come out first. If I need to set aside for taxes, that’s not part of the debt-payment budget either. I’m only interested in what’s actually left after all that, and from there I like picking a percentage before the money even comes in.

So if 80% of my usable side hustle income goes toward debt, a $500 month means $400 to debt and $100 for me. A really good $1,000 month means $800 to debt. I’m not renegotiating with myself every single time money shows up, and I can always change the percentage if life changes. It’s not a blood oath, it’s just a plan for the money. What actually matters to me is making sure more income actually improves my situation instead of just becoming more money I casually spend. I don’t want to make an extra $500 a month and somehow start spending $500 more a month, because then I’m just doing more work to stay in the exact same place.

Does an Extra $100 a Month Actually Make a Difference?

This one’s hard to believe when your debt balance is high. When you owe a lot, $100 can feel almost insulting. You send it, the balance moves a little, and you still owe a ridiculous amount of money.

But $100 a month isn’t just $100. It’s another $1,200 a year toward debt. $250 a month is $3,000. $500 a month is $6,000. And that’s before you even factor in the interest you avoid by knocking the balance down sooner. I’m actually working on a separate post that breaks down exactly what an extra $100 a month can do to credit card debt because I want to get into the real numbers. But the short version is I don’t think smaller extra payments deserve to get dismissed just because they aren’t dramatic. If $100 is what I’ve got, I’m using the $100.

Which Debt Should Get the Extra Money?

This gets more complicated once you’ve got more than one balance staring back at you. One option is putting extra money toward whatever has the highest interest rate, the debt avalanche method, which mathematically saves you more in interest because you’re going after the most expensive debt first.

The other popular option is the debt snowball, going after the smallest balance first. I get the appeal of both honestly. There’s something really satisfying about wiping an entire balance off your life and losing a whole minimum payment. But watching a card with a ridiculous interest rate eat my money every month also makes me want to go after that one first.

What matters most to me is that the extra money has an actual destination. If I’ve decided Card A is the target, that’s where it goes until I have a real reason to change the plan. Otherwise it’s way too easy to throw $50 here, $75 there, $100 somewhere else, and never actually feel like anything is moving.

Is Working More to Pay Off Debt Actually Worth It?

This is probably the question I care about most. I already have a job. I already have a life. I don’t want my solution to debt to turn into working every waking hour until it’s gone.

There are only so many hours in a day, and extra work costs something even when it doesn’t show up on a bank statement. It costs time, sometimes sleep, sometimes weekends or time with people I actually want to be around. And depending on the hustle, there can be real expenses too. So I don’t think every opportunity to make extra money is automatically worth doing. If I spend ten hours on something to make $60 after expenses, I need to actually decide if that $60 was worth ten hours of my life. Sometimes the answer is still yes, maybe I really need the $60. But I want to know what I’m trading before I say yes to it.

The side hustles I’m most interested in now are the ones that either pay enough to make the time worth it, can grow without needing the same amount of my time forever, or actually fit into my life without making everything else miserable. I don’t want to pay off my debt by building a life I hate living. I want the extra work to get me closer to needing less extra work.

See What Your Side Hustle Could Actually Do to Your Debt

This is exactly why I made the Side-Hustle-to-Debt Calculator.

I wanted to be able to plug in my actual debt balance, interest rate, and current payment, and then ask a simple question: what happens if I add my side hustle money on top of that?

TRY THE SIDE-HUSTLE-TO-DEBT CALCULATOR

You put in how much extra you’re making and choose what percentage you actually want to send toward debt, so you’re not pretending you’re going to throw 100% of it at the balance if that’s just not realistic for you. The calculator compares your current payoff timeline to what could happen once you add that extra income in, so you can see roughly how many months you could shave off and how much interest you could avoid. And you can just play around with it. Try $100. Try $250. Try $500. Try whatever you’re actually making right now. That’s way more useful to me than someone just telling me to “make more money.” I want to know what the extra money is actually buying me.

I Want My Side Hustles to Buy Back My Future Income

This is really what it all comes down to for me. I obviously want to make more money. But I don’t want the only result of making more money to be that I can afford to spend more money. I want some of it to actually change my financial situation.

Every debt I eliminate is one less payment taking a chunk out of my regular paycheck. One less minimum payment. One less balance collecting interest. One less company I owe money to every single month. Eventually that means more of the money I already make actually belongs to me.

That’s what I want the side hustle to buy. Not another bill. Not a more expensive lifestyle that requires me to keep hustling forever.

My own money back.

Should I Save Money While Paying Off Credit Card Debt?

Should I Save Money While Paying Off Credit Card Debt?

Trying to save money while also paying off credit card debt sometimes feels completely backwards. If my credit card is charging me a ridiculous amount of interest every single month, why on earth would I leave extra money just sitting in savings instead of throwing everything I possibly can at the balance? That’s the part I genuinely struggle with. I want this debt gone, and when I look at how much interest I’m paying, keeping money in savings feels like I’m sabotaging myself on purpose.

But the other option is leaving myself with absolutely nothing, and then the car needs something, the dog needs something, something in the apartment decides to break, or one of the million other things that cost money happens, and I’m right back to swiping the credit card I just worked so hard to pay down.

So for me the answer isn’t picking a side between saving money and paying off debt. I’m trying to figure out how to do both without being so cautious my debt barely moves, or so aggressive that one unexpected expense wrecks the whole plan.

Why I’m Not Sending Every Available Dollar to My Credit Cards

I love the idea of throwing everything at debt in theory. Get paid, pay the bills, keep exactly what I need to survive until the next paycheck, send everything else straight to a credit card. Very aggressive, very satisfying, right up until something happens, because something always happens.

If I send an extra $1,000 to a credit card and then get hit with a $700 expense I didn’t plan for, I need that $700 from somewhere. If there’s nothing in savings, odds are good it ends up right back on a credit card, and now I made this huge payment, felt like a whole finance queen for five minutes, and then added part of the balance right back on.

That’s exactly what I’m trying to avoid. I still want to be aggressive because high-interest debt is expensive and I’m not trying to drag this out forever, I just don’t think aggressive has to mean leaving myself completely exposed.

How Much Should I Keep in Savings While Paying Off Debt?

This is where financial advice starts getting annoying because there are so many random numbers floating around out there. Save $1,000. Save one month of expenses. Save three months. Save six months. Meanwhile I’m sitting here looking at a credit card charging over 20% interest thinking, you want me to leave HOW much sitting there while this thing eats me alive every month?

I get why a fully funded emergency fund matters, I really do, but I’m not convinced I personally need to wait until I’ve saved several months of expenses before I get serious about high-interest debt. What makes more sense for me right now is having enough of a cushion that one normal unexpected expense doesn’t immediately send me running back to a card.

And “enough” is going to look different depending on your life, obviously. Someone with an older car, kids, a house, inconsistent income, or one income holding up an entire household probably needs a bigger cushion than someone with way fewer financial responsibilities and rock solid income. This isn’t about hitting some perfect number because somebody on the internet said so. I just want enough sitting there that I can actually use it when something goes wrong without completely derailing what I’m doing with my debt.

Should I Use My Savings to Pay Off My Credit Cards?

This one is tempting, not gonna lie. If I have $5,000 sitting in savings and $5,000 sitting on a high-interest credit card, it’s hard not to look at those two numbers and think I could just make this whole problem disappear today. And depending on someone’s situation, using some savings to knock down high-interest debt might genuinely make sense.

What makes me nervous is the word all. Draining my savings all the way down to $0 just to watch a credit card hit $0 too would feel amazing for about a day, right up until I needed money for literally anything. Then what. If the answer is “put it on the credit card,” I didn’t actually solve anything, I just moved the problem around.

I’d rather figure out what I genuinely need to keep as a safety net first, and then decide if anything above that could do more for me against the debt. That’s probably not the mathematically fastest way to pay everything off, but I need a plan I can actually live with, not just one that looks good on paper.

Can I Save Money and Pay Off Debt at the Same Time?

This is what I’m actually doing. I’m not splitting everything perfectly down the middle, and I’m definitely not giving savings and debt equal priority right now, my debt is too expensive for that. But savings still gets a seat at the table.

When I get paid, I need to know what that paycheck actually owes me before I decide how much is going toward debt. There are bills coming out of it, I need money to live until the next one hits, something needs to go into savings, and I need enough of a buffer that I’m not budgeting myself down to my last $3 like it’s a personality trait. Then I can see what’s actually left for debt.

That number might not be as exciting as sending every cent I can find to a credit card, but it’s a lot more honest. And when I consistently have money left after handling all of that, that’s when I let myself get aggressive with it.

I Don’t Want My Debt Payment Creating More Debt

This is honestly the rule underneath everything else here for me. I don’t want to make a debt payment so aggressive that the payment itself is what forces me to go borrow money again.

If I already know I have $1,000 worth of expenses coming before my next paycheck, and I send that $1,000 to a credit card anyway because I want the balance to look better, that’s not discipline. That’s just me not leaving myself enough money for things I already knew were coming. The same goes for leaving myself no cushion at all.

I want my balances going down and staying down. That’s slower than the fantasy version where I send every spare dollar to debt and absolutely nothing unexpected happens for a whole year, but my life has never once agreed to follow one of my spreadsheets and I don’t expect it to start now.

Figure Out What Your Paycheck Can Actually Handle

This is one of the reasons I made my Paycheck-to-Debt Calculator. Instead of starting with “how much can I possibly send to my credit card,” it lets me start with what my paycheck actually needs to cover first.

I can put in my take-home pay, bills, everyday spending, savings contribution, the buffer I want to leave myself, and anything else that has to come out before the next paycheck lands.

TRY THE PAYCHECK-TO-DEBT CALCULATOR

Then I can actually see what’s left for debt without doing mental math every single payday. I can also play around with it, what happens if I put a little less into savings for a couple months, what happens if I find an extra $100 somewhere in the paycheck, what could consistently sending that toward debt actually do over time.

I don’t just want the biggest possible payment this Friday. I want a plan that lets me keep making progress next Friday too, and the Friday after that. If you want something that tracks all of this beyond just one calculation, I also built a Paycheck to Debt Command Center in Notion that does the same kind of paycheck breakdown but lets you actually manage it week to week instead of just running the numbers once.

I’m Trying to Stop the Cycle, Not Just Lower the Balance

Obviously I want my credit card balances lower, I want them at zero honestly. But I also don’t want to finally pay everything off and realize I never actually fixed the part where every unexpected expense turns into new debt. That’s why I’m keeping savings in the picture even while I’m being aggressive about the rest of it.

Maybe that means my payoff takes a little longer than it would if I emptied every account and threw all of it at the cards tomorrow. I’m okay with that if the tradeoff is having enough room to actually deal with life without immediately undoing my own progress.

I don’t need a perfect debt payoff plan. I need one that survives an actual Tuesday.

What to Do After Getting Laid Off: Your First 7 Days

Laid Off and Overwhelmed? Here's What to Actually Do in the First 7 Days

I’ve been at my current job for two and a half years, going on three now, and I do not take that for granted. Before this job, I got laid off from a company I actually loved working for, and it wrecked me more than some breakups have. I mean that seriously. I already deal with anxiety and depression, and losing that job did not just mean losing a paycheck. It meant losing a place I felt like I belonged, on top of suddenly having to make clear headed decisions about unemployment, health insurance, and next steps while my brain was doing everything it could to convince me I had failed at something.

That combination, grief over the job itself and the pressure to immediately function like a competent adult who has this handled, is what makes the first week of a layoff so brutal. Nobody warns you that you’ll be expected to fill out unemployment paperwork correctly while you’re also crying in your car. So this is the guide I wish someone had handed me back then.

When you get laid off, every single task feels urgent at the same time. Your income just changed, your routine is gone, and somehow you’re supposed to understand severance, unemployment, health insurance, bills, and job applications while you’re still processing what even happened.

Here’s the thing though. Not all of it has to happen today.

The first week isn’t about rebuilding your entire career. It’s about protecting the stuff that gets harder to fix the longer you ignore it: documents, deadlines, health coverage, cash, and access to information from your old employer. This is the plan I built from having actually lived through it, one that gives every decision its own place instead of dumping it all into one panicked pile.

A quick note before we get into it. Employment, unemployment, final pay, severance, and benefits rules all vary by state and by employer. Treat this as an organizational guide and confirm your specific deadlines with your state agency, plan administrator, HR department, or a professional who knows your situation.

Before you start, separate what’s urgent from what’s just loud

A layoff throws a long list of worries at you, but the loudest thought in your head isn’t always the most time sensitive one. You might feel pressure to apply to 30 jobs today, rewrite your entire LinkedIn, explain what happened to everyone, or decide whether it’s time for a whole new career.

That can wait. What generally can’t wait is saving your documents before you lose access to work systems, finding out when your paycheck and health coverage actually end, reading your severance paperwork closely enough to catch the response deadline, starting your unemployment claim, and figuring out how long your money can cover your actual bills.

Handle the deadlines first. The career reinvention can come later, once you know your immediate life is protected.

Day 1: Save your information and get the facts

Your first job isn’t applying for another job. It’s making sure you can still access what you need after your company shuts off your accounts.

Send yourself personal copies of anything you’re actually allowed to keep, to your personal email or a personal device. Don’t take confidential company info, customer data, or proprietary files, but do grab your separation or termination letter, the severance agreement and every attachment, recent pay stubs, your benefits summary and insurance contacts, performance reviews and any nonconfidential proof of what you accomplished, contact info for people who might serve as references, and any instructions about returning equipment or losing account access.

Before your access gets cut off, also do a few small things people forget in the moment. Screenshot or export any LinkedIn recommendations and Slack or Teams messages praising your work, since you will want that language later for your resume and you cannot get it back once you’re locked out. Save the personal cell numbers or emails of coworkers you’d want to stay in touch with, because company directories disappear with your login. And confirm your current mailing address is correct in HR’s system before you leave that conversation, since COBRA notices and other time sensitive mail will go to whatever address is on file, and a wrong address can cost you weeks you don’t have.

While you’re at it, ask HR directly for the dates that affect your money. When does your final paycheck arrive. How does your company handle unused PTO under their policy and your state’s law. Is severance on the table, and when do you need to respond by. What date does your medical, dental, and vision coverage actually end. When should you expect COBRA information. What happens to pending commissions, bonuses, stock options, or reimbursements. Who do you contact later about your 401k, HSA, FSA, or employment verification.

You don’t have to debate the layoff with HR in this conversation. You’re just there to leave with dates, documents, and contacts.

One thing I have to say as clearly as possible because it genuinely almost got me: check your mail. Actual physical mail, not just your inbox. COBRA election notices, severance paperwork, unemployment correspondence, and benefits deadlines still get sent by postal mail a lot of the time, and they will not wait for you to feel emotionally ready to open envelopes. I let mail pile up on my counter for almost two weeks during my layoff because I could not stand looking at anything that reminded me of it, and I nearly missed a coverage deadline because of it. Check it every single day during this first week, even the pieces that look like junk. Set a daily phone reminder if that’s what it takes.

Day 2: File for unemployment

Don’t wait until your severance runs out or your bank account gets uncomfortable to look at. Start with your state’s unemployment insurance program and let them tell you what you’re eligible for. The Department of Labor recommends contacting your state program as soon as possible after you become unemployed, since claims take time to process and you may need to complete weekly certifications or job search requirements while you wait.

Before you sit down to file, have your Social Security number, your employer’s legal name and address, your first and last dates of employment, your earnings info, the reason your employer gave for the separation, and your direct deposit info ready to go. Save your confirmation number, login info, filing date, and every single message the agency sends you. Filing the initial application isn’t the finish line, it’s the start of a process you’ll need to keep up with.

If your state or your company sets you up with a call or meeting with an unemployment or benefits caseworker to walk through your claim, do not miss it and do not let it get pushed to “whenever.” I cannot stress this enough. These caseworkers are often handling cases for dozens of people at once, and if you no show or ask to reschedule, you can end up waiting weeks to get back on their calendar, weeks you may not have before a filing deadline or certification window closes on you. Get the meeting on your calendar the moment it’s offered, put a reminder on it the night before and the morning of, and if you’re an emotional wreck that day like I was, go anyway. Write your questions down beforehand so you don’t have to think of them on the spot. If a meeting genuinely cannot happen at the scheduled time, call or email immediately, not the day after, to get a new one locked in before their calendar fills up. Losing that window is one of the most avoidable and most common mistakes people make in this first week.

Day 3: Pick a direction for health insurance

First things first, confirm the exact day your employer coverage actually ends. It might be your last day, the end of the month, or some other date buried in your plan documents. Don’t assume.

Then look at what’s actually available to your household. That’s COBRA or another continuation option through your old employer, a Marketplace plan through HealthCare.gov or your state’s exchange, getting added to a spouse or family member’s plan if that’s an option, or Medicaid or CHIP depending on your household income.

Losing job based coverage can qualify you for a Marketplace Special Enrollment Period, and HealthCare.gov says you generally have 60 days after losing coverage to enroll. COBRA gives you at least 60 days too, starting from whichever is later, the date coverage ends or the date you get the election notice.

Don’t just compare the monthly premium. Look at the deductible, what’s covered for prescriptions, whether your actual doctors are in network, any upcoming appointments you have, and what you’d realistically pay over the full year.

Day 4: Calculate your actual financial runway

This is the day you trade the vague fear of running out of money for an actual number you can work with.

Start by adding up what’s really available to you right now. Cash sitting in checking and savings, a confirmed final paycheck, confirmed severance and when it’s expected to hit, any unemployment benefits that are already approved (not just estimated), and any other reliable income coming into your household. Don’t build this number around a tax refund, hoped for freelance work, an unemployment amount you haven’t actually been approved for, or money someone else owes you.

Then list what it actually costs to keep your life running. Housing and utilities, food and essential household stuff, your insurance premiums, medication and necessary health expenses, transportation and phone and internet you need for work or job hunting, and your minimum required debt payments or court ordered obligations.

The CFPB’s guidance is to prioritize whatever protects your housing, income, insurance, and legal obligations, not whichever company happens to be calling the loudest. If you genuinely can’t make a payment, reach out to the company before you go quiet and ask what hardship options they actually have.

Once you have both numbers, divide the money you can safely use by your trimmed down monthly expenses. That’s your runway. It’s not a prediction of exactly how long you’ll be unemployed, it’s a planning window that tells you how aggressively you need to cut back and when you might need extra support. This is also the day to cancel or pause anything nonessential, redirect autopay off accounts that are about to get tight, and write down every due date so nothing sneaks up on you. Don’t panic pay down big balances before you actually know what the next few months need from you.

Day 5: Go back for the benefits and money you left behind

Getting laid off separates you from a company. It doesn’t automatically erase every account or benefit tied to that job, and it’s easy to lose track of what’s still yours.

Confirm where your retirement account is staying and how you’ll access it. Ask about your HSA access and any FSA deadlines for submitting expenses. Look into life or disability insurance conversion options if they’re offered. Check the vesting and exercise deadlines on any stock options or equity. Submit any reimbursable expenses you haven’t turned in yet, and make sure your mailing address is updated for tax forms.

Try not to cash out a retirement account just because it’s sitting there and available. The IRS is clear that a withdrawal can trigger income taxes, and depending on your age and account type, an early distribution penalty on top of that. Look at your options, leaving it in the plan, rolling it into a new employer’s plan, or a rollover into an IRA, before you decide anything.

Day 6: Build your job search foundation

Now you can actually start preparing to apply, without turning the whole day into a frantic scroll through every job with a salary attached.

Write down two or three job titles that genuinely match your experience and what you’re actually willing to do next. This keeps your resume, your search terms, and your applications all pointed the same direction instead of scattered everywhere.

You don’t need a totally different resume for every single application. Build one strong, accurate master version with your best results, then tweak the summary, skills, and most relevant bullets for whatever opportunity you’re actually serious about.

While your memory is still fresh, write down the projects you led or improved, any revenue, time, cost, retention, or quality results you can point to, the systems and tools you actually used, positive feedback or performance review language, and specific problems you solved. Update your LinkedIn enough that it reflects your latest role and makes you findable. You do not have to post a vulnerable layoff announcement unless you genuinely want to.

Day 7: Build a system you can actually keep up with

By day 7 you don’t need a job offer yet. You need a system that keeps deadlines, applications, and follow ups from living entirely in your head.

That means a short list of priority roles and companies, a realistic number of thoughtful applications you can actually keep up week to week, somewhere to log the job description, salary, date applied, contact, status, and follow up date, a weekly check in on your benefits and money, and dedicated time away from job searching so it doesn’t quietly become unpaid, all consuming labor.

The goal was never to prove you’re working hard enough to deserve another job. It’s to make good decisions over and over while protecting your energy and your household.

A calmer place to keep all of this

The hardest part of a layoff is that the information ends up everywhere. Benefits in one email, severance in a PDF, bills in your banking app, applications spread across browser tabs, follow up dates floating around in your head.

That’s exactly why I built the Layoff Survival Toolkit, a $7 Notion template made for people who just got laid off and need one calm place to organize benefits, deadlines, bills, financial runway, job applications, follow ups, and what the next 30 days actually look like.

You can absolutely build your own version of this in a spreadsheet or a notebook. The point isn’t the tool, it’s that you stop relying on memory during a week when your brain is already carrying too much.

What can honestly wait until after week one

Rewriting every line of your LinkedIn. Choosing a whole new career path. Buying a course or certification because you feel behind. Applying to every job you can find. Posting a public explanation of what happened. Making a permanent call on your retirement account without weighing the consequences. Pretending you’re fine so everyone else feels more comfortable.

Some of that might matter eventually. None of it matters more than your immediate deadlines, your coverage, and keeping yourself financially stable this week.

A few questions people usually ask


How soon should I file for unemployment after a layoff?

As soon as you can. Contact your state program right away, since eligibility and waiting periods vary and delaying your filing only delays the process. Keep up with any required certifications after that first claim goes in.

Should I sign my severance agreement right away?

Not just because it landed on your desk. Actually read the deadline, the compensation and benefits terms, the release language, confidentiality provisions, and any restrictions. If anything is unclear or the situation feels disputed, it’s worth getting legal advice before you sign.

How long do I have to pick health insurance?

It depends on the option. A Marketplace plan after losing job based coverage generally gives you a 60 day window. COBRA gives you at least 60 days too, starting from whichever comes later, losing coverage or getting the election notice. Always confirm the exact dates in your own paperwork.

Do I need to start applying for jobs on day one?

Not really. Protecting your documents, benefits, deadlines, and financial runway matters more early on. By the end of week one, aim to have a clear target, one strong resume, and a system for tracking things, so your applications are intentional instead of scattered.

What if I can’t pay every bill?

Prioritize whatever protects your housing, utilities, insurance, transportation, food, health, and legal obligations. Reach out to lenders and service providers before you miss a payment if you can, and ask what hardship options exist. Local help might also be available through 211, housing counselors, or state and community programs.

Final thoughts

Being laid off isn’t one task, it’s an emotional gut punch, a financial shift, a benefits transition, and eventually a job search, all layered on top of each other. Trying to solve all four at once is exactly how it starts feeling impossible.

For the first seven days, protect whatever has a real deadline. Save what you might lose access to. Find out exactly when the money and insurance stop. File the claim. Calculate your runway. Then build a job search system you can actually live with, not one you’ll abandon by week two.

I won’t pretend the anxiety and the grief go away just because you have a checklist. They didn’t for me. But having something concrete to hold onto on the days my brain was not cooperating is what got me through that stretch, and it’s the reason I’m two and a half years into a job I’m actually grateful for now. That part does get better, even when the first week feels like it never will.

You don’t need your whole future figured out by next week. You just need to see the next right step in front of you.
Is Redbubble Worth It in 2026? What 69 Sales Actually Paid Me

I Made $81.51 on Redbubble. Here's What Actually Sold and What I Got Paid

I have not made thousands of dollars on Redbubble. I haven’t even hit $100 in artist earnings yet. What I have done is upload 92 designs, sell 69 products, and rack up $81.51 in artist margin, mostly without lifting a finger to promote the shop.

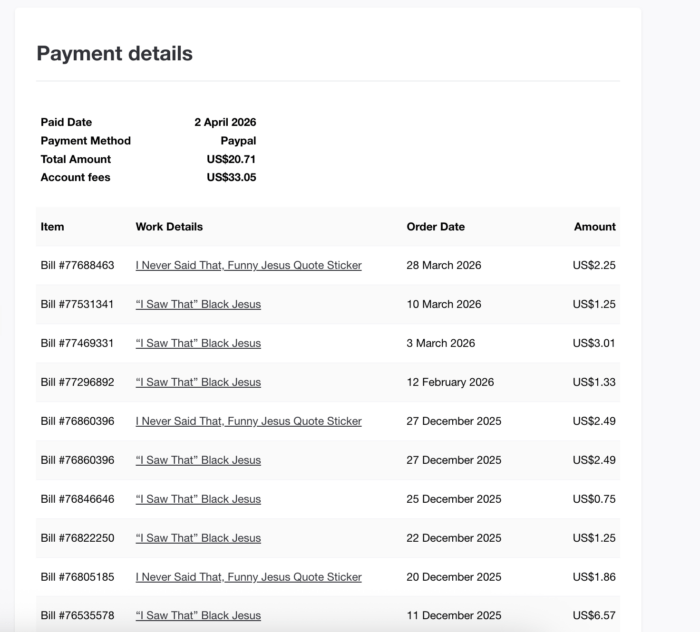
My first actual payment was a lot smaller than that. $20.71.

That gap is exactly why I wanted to write this. Redbubble income sounds simple until you start separating out the number of things sold, the margin your dashboard shows you, the fees that get deducted, and what actually lands in your PayPal account. Those are four different numbers, and I didn’t fully understand that until I sat down and pulled all of mine together. If you’ve read my Broke Tax breakdown, you already know I’m big on showing the real numbers instead of the version that sounds better.

I opened my Redbubble shop sometime around 2024. Honestly I can’t remember the exact date. I made a handful of Pinterest pins for it early on, but my cannabis related pins kept getting flagged, so I deleted them and basically stopped promoting the shop at all.

The sales still came in. Slow, but real, and mostly organic.

Here’s what actually sold, what I earned, and why I’m now thinking about taking my bestselling sticker ideas somewhere other than Redbubble.

This reflects my personal results as of August 4, 2026. Redbubble changes its fees and payment policies pretty often, so check their current terms before you open a shop.

The numbers, all together

Right now my shop sits at 92 uploaded designs and 69 products sold, for $81.51 in cumulative artist margin. Redbubble’s sales history also shows $5.88 in taxes collected, which isn’t income to me since Redbubble collects and remits sales tax where it’s required to.

The $81.51 and the $20.71 payment aren’t from the same period, and I want to be clear about that because it confused me too when I first looked at it. My first payment period covered $53.76 in artist margin. Redbubble took $33.05 in account fees out of that and paid me the remaining $20.71 on April 2, 2026.

After that payment period closed, the shop made another $27.75 in artist margin. That hasn’t been paid to me yet. Redbubble is currently showing $22.50 in fees against those newer earnings, which leaves my account balance sitting at $5.25. No second payment yet, as of today.

So the $81.51 people might assume I’ve pocketed isn’t cash in hand. What I’ve actually received is $20.71. The rest is either fees or an unpaid balance still sitting in my account.

What actually sold

Uploading 92 designs did not mean I had 92 good ideas. A handful of designs did almost all the work.

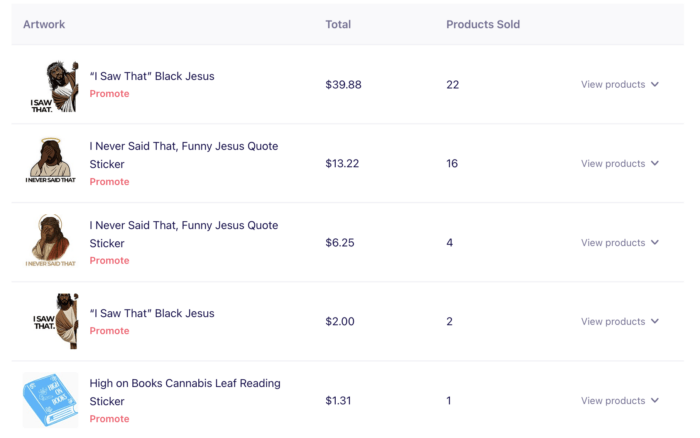
My “I Saw That” Black Jesus sticker, first listing, sold 27 times and brought in $43.66 on its own. The second listing of that same design added another 8 sales and $10.27. My “I Never Said That” sticker sold 16 times on its first listing for $13.22, plus 4 more sales worth $6.25 on a second listing. My Merry Christmas Yorkie listings picked up 9 sales for $4.99. Everything else, a cannabis leaf reading sticker, a coffee and weed design, a fall Yorkie, a wake and bake sticker, added up to a little over $2 combined.

Add it up and the four listings tied to my two Black Jesus concepts brought in 55 of my 69 sales and $73.40 of my $81.51 in margin. That’s around 80% of everything sold and roughly 90% of the money, from designs built around basically one idea.

Why the Black Jesus stickers did the best

I’d seen a similar style of sticker floating around and wanted to make a version with Black Jesus specifically. That small change mattered more than I expected. It was recognizable, funny, and a lot more representative of what I actually wanted to see out there instead of another generic quote sticker.

I can’t tell you exactly why each person bought it, but the results speak for themselves. It outsold everything else in my shop, cannabis stickers, book stuff, my Yorkie designs, by a wide margin.

I’m not saying everyone needs to make religious humor or copy whatever’s trending in someone else’s shop. What I took from it is that specificity gives people an actual reason to pick your design over the hundreds of similar ones sitting next to it. “Funny sticker” is vague. A funny sticker featuring Black Jesus speaks to a very specific person, and that person bought it.

Were these sales even organic?

For the most part, yes. I made a few Pinterest pins when I first opened the shop, but I never kept up a real promotional strategy. Once some of my cannabis pins got flagged, I deleted them and stopped depending on Pinterest to send people to Redbubble. I never ran ads or pushed an existing audience toward the shop either. These 69 sales mostly came from strangers finding my stuff inside Redbubble’s own marketplace.

That’s honestly encouraging. People I’ve never interacted with liked something enough to buy it.

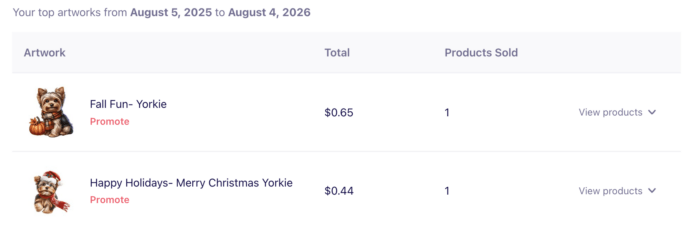
It’s also revealing in a less fun way, because my sales have basically stopped. The shop is still open, but from August 2025 through today, only two designs even showed up in my top artwork report, one sale each. I can’t prove Redbubble changed how it’s showing my listings, but without my own audience or steady outside traffic, I don’t have much control over whether people ever see my work again.

That’s the real downside of building a shop entirely inside someone else’s marketplace. You’re at the mercy of their algorithm, and you find out how much when it stops sending people your way.

My first payment, and what happened after

My first Redbubble payment hit PayPal on April 2, 2026. The total paid was $20.71, and the account fees listed on that same statement were $33.05. So the earnings behind that payment were $53.76 before fees, and around 61.5% of it got taken off the top.

Seeing $33.05 in fees next to a $20.71 payout was a little deflating. I get that Redbubble is handling the marketplace, printing, and shipping, but it’s hard to feel like meaningful income when more than half of it disappears before it reaches you.

After that first payment, the shop kept making occasional sales, adding another $27.75 in margin. But the payment history is now showing $22.50 in fees against that, leaving a balance of $5.25 that I haven’t been paid yet. As of today, the only money Redbubble has actually sent me is that original $20.71.

That’s the whole reason I’m writing this the way I am. An earnings dashboard is not the same thing as money in your account. When I say I made $81.51, I mean that’s the cumulative margin shown across all 69 sales, not $81.51 that’s landed in my PayPal.

For anyone wondering how the fee structure works, Redbubble currently splits accounts into Standard, Premium, and Pro tiers. As of July 31, 2026, Standard artists pay a 50% platform fee, Premium pay 20%, and Pro pay none, with Standard and Premium also facing an extra fee on markups above 20%. You can read Redbubble’s own breakdown of account tiers and how payments get calculated if you want the specifics, since those policies can and do change. What I’m sharing here is my real result from my actual statement, not an estimate based on the current chart.

Redbubble also dropped its payment threshold from $20 to $10 starting July 1, 2026, applied after fees are taken out.

Did I fail at Redbubble?

No, but I also wouldn’t call $81.51 a real income stream.

I put up 92 designs and made 69 sales without already having an audience. That told me two things. People I don’t know were willing to pay for something I made, and a small number of specific ideas had way more potential than the rest.

That’s genuinely useful information. What I did wrong was letting Redbubble be the entire business instead of treating it like a place to test what people want. If I’d built traffic around the winning designs, or sold my bestselling stickers somewhere I actually controlled the customer relationship and kept more of the profit, I think I’d have a very different number to report.

Redbubble handled the annoying parts. I never bought inventory, packed an order, or shipped anything. But that convenience came with thin margins and almost zero control over whether anyone actually sees what I make.

Is it worth it in 2026?

I’d say yes, under two conditions.

It’s genuinely useful if you want low risk experience putting your work into a real marketplace. You get to see what strangers actually respond to and test ideas without spending money on inventory first.

It also makes more sense if you already have an audience you can send to your shop. If you’re relying entirely on Redbubble to bring you customers, your sales are at the mercy of whatever their algorithm decides to show, and you have basically no say in that.

I wouldn’t recommend uploading a ton of designs and assuming passive income just happens. I uploaded 92 and two closely related ideas made almost 90% of my money. Redbubble was a solid testing ground. I’m just not convinced anymore that it should be the final home for my best stuff.

What I’d do differently

If I were starting over, I’d pay attention to early signs of demand a lot faster. The moment the Black Jesus designs started clearly outselling everything else, I should have treated that as real market research, better photos, content built around that collection, and a sales channel where I had more say over who saw it and what I kept.

That’s what I’m considering now. Instead of uploading more designs and hoping Redbubble decides to promote them, I’m thinking about ordering my bestselling stickers myself and selling them somewhere I can actually put some intention behind getting eyes on them.

That means upfront cost and the hassle of holding and shipping inventory myself, so I wouldn’t start with hundreds of stickers. A small test order would let me check the quality, figure out my real profit per sticker, and see if people will buy directly from me instead of through Redbubble.

The goal isn’t to throw away what Redbubble proved. It’s to actually use it, especially since every bit of extra income matters when you’re juggling more than one type of debt on a single income like I am.

Quick answers, since people always ask


How much did I make from Redbubble?

$81.51 in cumulative artist margin from 69 products sold, as of August 4, 2026. $53.76 of that was tied to my first payment period, and another $27.75 came in afterward, with $22.50 in fees against it and a current balance of $5.25.

How much was my first payment?

$20.71 through PayPal on April 2, 2026, with $33.05 in account fees showing on that same statement.

Have I gotten all $81.51?

No. I’ve received one payment of $20.71. The rest is either fees or sitting in my account as an unpaid $5.25 balance.

How many designs did I upload?

92. Most never sold. Two related Black Jesus concepts brought in 55 of my 69 total sales.

Can you sell on Redbubble without an audience?

I did. I made a few Pinterest pins early on and deleted them pretty quickly, so almost everything came through Redbubble’s own marketplace. That said, sales have slowed a lot, and I don’t have another source of traffic to fall back on.

What sold best?

My Black Jesus designs, no contest. Those four listings brought in $73.40 of my $81.51 total.

Is this passive income?

It can keep making sales after the upload work is done, but I wouldn’t call it reliable or guaranteed. Visibility can change, fees eat into what you make, and most of what I uploaded never sold at all.

Final thoughts

I didn’t hit the big dramatic numbers people throw around in “how to make money on Redbubble” posts. I made $81.51 in cumulative margin. I got paid $20.71 of that. Another $27.75 came in after, but $22.50 in fees left me with a $5.25 balance I’m still waiting on. And 92 uploaded designs mattered a lot less than just finding two ideas people actually wanted.

That’s not a failure. It’s proof that there’s demand, just on a small scale right now.

My next move isn’t uploading another 92 designs. It’s taking the ones that already proved themselves, putting them somewhere with more eyes on them, and keeping more of what they’re worth.

You can check out my shop, AshleyJaneCo on Redbubble, if you want to see what’s still up!

You Are Not Bad With Money. The Math Just Does Not Work Anymore.

You Are Not Bad With Money. The Math Just Does Not Work Anymore.

I paid a few hundred dollars toward one of my credit cards. Felt good about it. Went to bed.

Woke up the next morning and the interest had already come through. A couple hundred dollars. Just like that. Gone. Like the payment I just made barely even counted.

I wanted to scream. And I know I am not the only one who has typed “why can’t I get ahead financially” into Google at midnight because the numbers just are not adding up no matter what you do.

Not because you did something wrong. Not because you are irresponsible. Because you are doing the thing you are supposed to do and the numbers are still moving in the wrong direction. That feeling of doing everything right and watching it not matter is one of the most frustrating things I have ever experienced with money. And I know I am not the only one sitting with it.

The Story We Were Told Does Not Add Up Anymore

We grew up with a pretty clear script. Work hard. Get educated. Get a good job. Pay your bills on time. Stay out of trouble financially and you will be fine.

Nobody updated the script when the cost of everything started climbing and the paychecks did not keep up. Nobody told us that doing it all right could still leave you behind. That you could have a real job, a real income, real intentions, and still be watching your debt barely move while the interest keeps stacking.

That is not a character flaw. That is just math that was never set up in your favor.

Groceries cost more. Rent costs more. Gas costs more. Everything you need to just exist is more expensive than it was a few years ago. And if your income has not grown at the same rate, which for most people it has not, then you are already starting every month in a hole you did not dig yourself.

Add debt with real interest rates into that picture and the math gets even uglier. You make a payment. Interest charges. You make another payment. Interest charges again. It feels like you are running on a treadmill that keeps speeding up no matter how hard you push.

Why It Feels Like Drowning

There is a specific kind of hopeless that comes from trying and not seeing it work. It is different from not trying. When you are not trying you can at least tell yourself that things would be different if you did. But when you ARE trying, when you are making the payments and watching the numbers and doing the thing, and it still feels like nothing is changing?

That is when the spiral starts. Maybe I am just bad with money. Maybe I will always be in debt. Maybe this is just what my life is. I have been in that spiral, shoot I’m still in that spiral. It is a lying spiral. It takes real circumstances, real economic pressure, real systemic garbage, and turns it into a story about your worth. And once you are in it, it is hard to see clearly enough to figure out what would actually help.

You are not drowning because you are doing it wrong. You are drowning because the water level keeps rising and nobody warned you to get a boat.

What Is Actually Happening With That Interest

When I saw that interest charge come through the morning after my payment I had to just sit with it for a minute. Because it genuinely felt like a punishment for trying.

That is kind of exactly what high interest debt is. It is a system designed to make sure that the longer you are in it the harder it is to get out. The minimum payment is calculated to keep you in the cycle as long as possible. The interest compounds in a way that is specifically designed to work against you if you do not have a strategy.

It is not personal. The credit card company is not targeting you specifically. But it is also not an accident. It is working exactly as designed. Which means getting out of it requires working against the design on purpose. That takes a system. Not willpower. Not shame. A system!

What I Want You to Take From This

You are not bad with money.

You are a person trying to manage money in an economy that has gotten genuinely harder to navigate. You are dealing with interest rates and inflation and stagnant wages that have nothing to do with your discipline or your worth.

The frustration you feel is valid. The wanting to scream is valid. The feeling of being stuck in a cycle you cannot figure out how to break is valid. But stuck is not the same as permanent.

If you are at the point where you are ready to stop just surviving the cycle and start building something to fight back against it, I wrote about exactly that. The Broke Tax is what I built for myself when I got tired of watching my payments disappear into interest and needed something that could actually hold the whole picture in one place. It is not a magic fix. Nothing is. But it is a system, and a system is what the math actually requires. You can check out that system here.

If you are not ready for a system yet, that is okay too. Sometimes you just need to know that someone else is frustrated and in it and still going. I am here. I am documenting all of it. You are not alone in this!

The Broke Tax Is Real. Here Is What I Built to Fight Back Against It.

The Broke Tax Is Real. Here Is What I Built to Fight Back Against It.

There is a thing that happens when you carry debt long enough that nobody really talks about. You stop being broke because of a bad decision. You start being broke because of math. The interest charges, the late fees when things stack up wrong, the overdraft you did not see coming because you forgot about that automatic payment. None of it feels like a mistake anymore. It just feels like the way it is.

That is the Broke Tax. The invisible surcharge that gets added to your life when your debt load is heavy enough that you cannot quite get ahead. You are paying more than you owe because you owed it in the first place.

I tried to do it right. The way they told me to. Go to college, get a job, get the graduate degrees so you can get the raise. Do all of that and you still end up in debt. Deep debt. And do not even get me started on the credit cards. Every payday my check was disappearing into bills and payments before I could blink, and I kept telling myself that something had to change.

So I made something, a system that I’m using that is starting to work.

What Being In Debt Actually Feels Like From Inside It

People talk about debt like it is mostly a math problem. Add up the balances, pick a payoff method, execute. And yes, eventually it is a math problem. But it does not feel like math when you are in it.

It feels like a cloud that follows you around. You are at a dinner with people you love and somewhere in the back of your brain there is a number running. You get a nice paycheck and for about twenty minutes you feel relief and then you remember what it has to cover. You want to do something for yourself, something reasonable and small, and you run a whole internal calculation before you let yourself have it.

I am irresponsible with money. I am surviving a season of life that cost more than I expect and taking the time to build a career that pays what I deserve. A lot of people reading this are in exactly the same position. The debt did not happen because you are bad with money. It happened because life is expensive and income does not always catch up on schedule.

That is worth saying out loud because the shame of it is what keeps most people from actually doing anything. You cannot solve a problem you are too embarrassed to look at directly.

The Moment I Got Honest About the System I Was Missing

I had been doing the thing where I knew roughly what I owed but not exactly. Knew roughly what my bills were but not precisely. Knew I was supposed to be putting more toward debt but could not always tell you why the money was gone before I got there.

The problem was not discipline. I have plenty of that in other areas of my life. The problem was that I did not have a system. I was reacting to my money every payday instead of directing it. There is a huge difference between those two things and I spent longer than I want to admit figuring that out.

What I needed was something that could hold all of it in one place. Not a complicated budget. Not a spreadsheet that requires a finance degree to maintain. Just a clear, real, honest accounting of what I owe, what I make, and how every dollar gets assigned before I spend a single one of them. So I built it.

What I Made and Why I Made It This Way

The Broke Tax is the workbook I made for myself and then realized I needed to share because I know I am not the only person who needed it. It is 45 pages and it is not fluff. Every section does something specific.

It starts with a Debt Reality Check because you cannot work on something you have not looked at fully. Not the vague sense of what you owe. The actual number. Every balance, every interest rate, every minimum payment, written down in one place for the first time.

Then it walks you through picking a payoff method that actually fits your life, not just the one that is technically most efficient on paper. There is a big difference between the method that works in theory and the one you will actually stick to for two years.

The Paycheck Assignment section is the part I use every single payday. You assign every dollar of your check before you spend anything. Bills, debt payments, essentials, and then whatever is left. It sounds simple. It changes everything.

There is a Short Paycheck Protocol for the months when things get tight, a Spending Audit that is not judgmental, an Income Unlock Plan for looking at what additional income might actually be realistic for your life, a full monthly progress tracker, and a 30-day kickstart plan to get you moving in the first two weeks.

It also has motivational pages because I know that the mindset piece is not separate from the strategy piece. You will not follow through on a plan you do not believe in. The workbook accounts for that.

Who This Is For

This is for the person who makes decent money and still feels broke. The person who knows they need to deal with the debt but has been putting off really looking at it. The person who has tried budgets before and found them unsustainable.

It is not for someone in a financial crisis who needs a credit counselor. It is for someone who is stable, working, and ready to stop letting debt just happen to them every month.

If that is you, this is the thing I wish I had had two years ago.

The Broke Tax is a 45-page printable workbook available in my Gumroad shop for $17. It is also on Etsy. Print it once, use it for as long as you need it.

One More Thing

The Broke Tax is real. It costs you real money in interest and fees and the mental overhead of carrying debt that never seems to move. But it is not permanent and it is not a character flaw.

And if you have ever been told to just budget better, I already wrote about why that advice misses the point entirely. You just need a system that works for your actual life. This one works for mine.

If you have been putting off looking at the full picture, this is the nudge. Go grab the workbook. Do the Debt Reality Check page first. Just that one page will shift something. I know because it was the first time in a long time I felt like I actually knew what I was dealing with instead of just guessing. Still working on it, and I will be documenting everything right here as I go! 

I Have Three Types of Debt and a 9-to-5 That Does Not Cover All of It. Here Is What I Am Actually Doing.

I Have Three Types of Debt and a 9-to-5 That Does Not Cover All of It. Here Is What I Am Actually Doing

Nobody tells you this part. They celebrate the degree. They ask what is next. And somewhere in the back of your mind you are doing the math on what all of it actually cost. The tuition, yes. But also the credit cards you leaned on when money got tight. The personal loan that covered the gap. The student debt that was just supposed to be normal.

I did everything right on paper. I stayed in school, got the degrees, built the resume. I came out the other side with a 9-to-5 job I am grateful for and a debt load that does not quite match the life I thought I was building toward. Credit cards, a personal loan, student loans. The full set.

So here we are!

This post is not a success story with a clean ending. I am in it right now. Some months I hit my targets and some months something unexpected happens and I am recalibrating. What I can offer is a real system that is actually working, the mistakes I made before I figured it out, and the specific things I do every payday to keep moving forward without making myself miserable.

If you are dealing with multiple debts on an income that does not feel like enough, this is for you.

First, the Honest Picture of Where I Started

Before I could do anything useful with my debt I had to actually face what I owed. Not a vague sense of it. The real numbers.

I sat down with every account open and wrote four things for each debt:

  • The current balance
  • The interest rate
  • The minimum payment
  • The due date

That list was uncomfortable to make. It was also the first time I had been in the same room as my actual financial situation in a long time. Something about seeing it all on one page made it feel more like a problem to solve and less like a cloud of dread following me around.

If you have not done this yet, that is your first move. Not a budget. Not a debt payoff calculator. Just a list. Four columns, every debt. That is it.

The Three Rules I Set Before I Made Any Other Decisions

Once I had the full picture I made three rules for myself before I started building a plan. These came from watching myself fail at other attempts where I skipped this part.

Rule 1: Minimum payments are not negotiable.

Every debt gets its minimum payment every month before anything else happens. Missing minimums damages your credit score, adds late fees, and can trigger penalty interest rates that make your situation worse. There is no strategy worth risking this.

Rule 2: The plan has to include my actual life.

I am not going to stop buying books or cancel every social plan for two years to pay off debt faster. I have tried versions of that and they do not hold. A sustainable plan is one I can actually run month after month. So my budget includes real spending money for the things that matter to my quality of life. Not unlimited. But real.

Rule 3: Progress is progress, even when it is small.

On months where I can only cover minimums, that is what I do. Keeping everything current when that is genuinely all I can manage is not failure. It is maintenance. It keeps the situation from getting worse while I figure out the next move.

The System I Use Now

Every payday I do what I call a paycheck reset before I spend anything. It takes about fifteen minutes and it has changed how I relate to money more than any other habit I have built. Here is the short version:

  • Write down the actual amount that hit my account after taxes
  • Subtract every fixed bill and minimum payment due before next payday
  • Decide deliberately if there is any extra to throw at one target debt
  • Set my living budget for the rest of the pay period from what is left
  • Check in briefly at the end of each week to stay on track

That is it. No complicated spreadsheet. No tracking every coffee. Just a clear picture of what I am working with and a conscious decision about where it goes.

I go much deeper on this in the paycheck reset post, which is worth reading if you want the full breakdown.

How I Decided What to Pay Extra On First

With minimums covered the question becomes where to put any extra money. I use a hybrid approach.

I picked one target debt based on two things: the interest rate and how close it is to being gone. A debt that is nearly paid off and also has a high rate is a good early target because you get the psychological win of eliminating it and you stop the interest bleeding quickly.

I do not stress about optimizing this perfectly. The best debt payoff strategy is the one you actually stick with. If seeing a balance hit zero keeps you motivated, pay the smallest first. If knowing you are saving the most money long term keeps you going, attack the highest rate. Either works better than doing nothing.

One More Thing About Having Multiple Types of Debt

Credit cards, personal loans, and student loans all behave differently. Credit cards tend to have the highest interest rates so they cost you the most the longer they sit. Personal loans usually have fixed terms so you know exactly when they end. Student loans have the most options, including income-based repayment plans and pause options, depending on your situation.

Understanding the type of debt you have changes how you prioritize it. I always recommend calling your student loan servicer directly if you are struggling because there are more options available there than most people know about.

Where to Start If You Are Just Getting Here

Make the list. Four columns, every debt, today. Not tomorrow. Today.

Then come back and read the paycheck reset post because that is the habit that actually moves everything forward. Everything else in High Debt builds from that foundation.

This is a slow process. It is not linear. But it is absolutely possible on a regular income without extreme sacrifice, and that is exactly what I am proving month by month.

The Paycheck to Debt Decision Planner in the shop is the three-page tool I use for my payday reset every single month. It is $5 and you can use it starting this paycheck.