Author: Ashley Jane
How to Make Infused Popcorn (Easy Cannabutter Snack)
How to Make Infused Popcorn (Easy Cannabutter Snack)
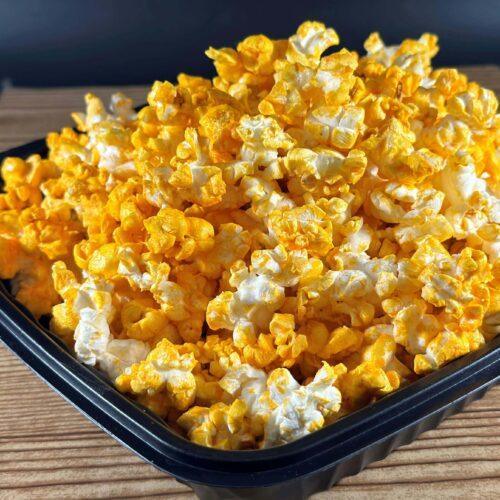
There’s something about infused popcorn that feels comforting in a way most infused edibles don’t. It’s warm, familiar, and doesn’t require you to commit to a whole dessert situation. That’s exactly why infused popcorn is one of my favorite low-effort edibles to make, especially when I want something cozy but don’t feel like baking or cleaning up a bunch of dishes.
This is very much a girl dinner edible. But probably with a refreshing non-infused beverage not some wine (but no judgement if you want it!). You don’t need fancy equipment, you don’t need to be good in the kitchen, and you definitely don’t need to turn it into a project. If you can make popcorn and melt butter, great news! You’re already qualified!
Quick note before we get into it: this is for adults 21+ only, where cannabis is legal. Go slow, dose intentionally, and don’t let how easy this is trick you into overdoing it.
What is infused popcorn?
Infused popcorn is exactly what it sounds like: popcorn coated with butter or oil that’s been infused with cannabis. Instead of baking THC into something complicated, you’re adding it to something you already eat casually.
What I like about it is how flexible it is. You’re not locked into one serving size, and you don’t have to finish it all at once. You can eat a handful, wait, see how you feel, and decide if you want more. That alone makes it feel way less intimidating than brownies or cookies.
It’s also one of the easiest ways to make edibles that still feel normal. Nothing about infused popcorn feels extra or performative. It’s very “I’m on the couch, the lights are low, and I just want to relax.”
Why popcorn works so well for edibles
Popcorn is forgiving. The butter spreads easily, the texture stays light, and it’s simple to portion without overthinking it. Unlike baked edibles, you’re not guessing how strong one square or one cookie might be. It’s also customizable without feeling like a recipe project. Sweet, salty, spicy, cheesy, whatever mood you’re in, popcorn can match it with almost no effort.
How to Dose Infused Popcorn Safely
The easiest way to control infused popcorn is to infuse the butter, not the popcorn itself. That way, you’re not guessing or unevenly dosing the bowl.
If you already have cannabutter, you’re good to go. If not, you can use my cannabutter recipe here!
For popcorn, I recommend keeping it light. This is a snack, not a “cancel your plans” edible.
A good range:
- 5-10 mg per bowl for a cozy, noticeable high
- 2.5 mg per bowl if you’re sensitive or just want a soft background buzz
Example, no stress math:
If your cannabutter is about 20 mg per tablespoon and you use 1 tablespoon total, that’s 20 mg in the whole batch. Split that into 4 bowls and you’re at 5 mg each.
You don’t need perfect numbers. You just need to be intentional.
How to Make Infused Popcorn at Home
I pop the popcorn however is easiest that day. Sometimes stovetop, sometimes an air popper, sometimes straight from the microwave. The only thing I try to do is keep it plain so the infused butter can shine.
While the popcorn is popping, I melt butter on low heat. Not sizzling, not browning, just melted. Most of the time I do a mix of cannabutter and regular butter so the dose stays reasonable and the flavor stays smooth.
Once the popcorn is ready, I drizzle the butter slowly, toss it, drizzle again, toss again. This part matters. Dumping it all in one spot is how you end up with one dangerously strong corner and the rest dry. From there, season however you want.
Flavor Ideas That Still Feel Elevated
If I want classic cozy, it’s just butter and salt. Sometimes a little nutritional yeast if I want that cheesy movie-night vibe. For sweet girl dinner energy, cinnamon sugar or a light cannahoney drizzle works without turning it into dessert. For a savory, grown vibe, smoked paprika, garlic powder, and a pinch of cayenne is elite with popcorn!
A quick tip so you don’t overdo it
Popcorn is easy to keep eating, especially when you’re relaxed. If you know you snack mindlessly, make two bowls:
- one infused
- one non-infused
Eat the infused bowl slowly, wait, see how you feel, and then keep snacking without accidentally doubling your dose. It’s the easiest way to stay comfortable and enjoy the night.
How Long Does Infused Popcorn Take to Kick In?
Like most edibles, infused popcorn can take anywhere from 30 to 90 minutes to fully kick in. Metabolism, tolerance, and whether you’ve eaten recently all play a role. Give it time before assuming it “isn’t working.”
How to Store Infused Popcorn
Store infused popcorn in an airtight container at room temperature for up to 1–2 days. It’s best fresh, but it will hold overnight. Keep clearly labeled and away from children or pets.
Infused popcorn doesn’t feel like a project. It feels like something you can make on a random evening without planning ahead. It’s warm, flexible, and familiar, and honestly, that’s what I want most of the time. I’m just figuring out what feels good and manageable in this season. If you’re building your own cozy edible rotation, I’ll keep sharing what works for me here in Tasty Tokes.
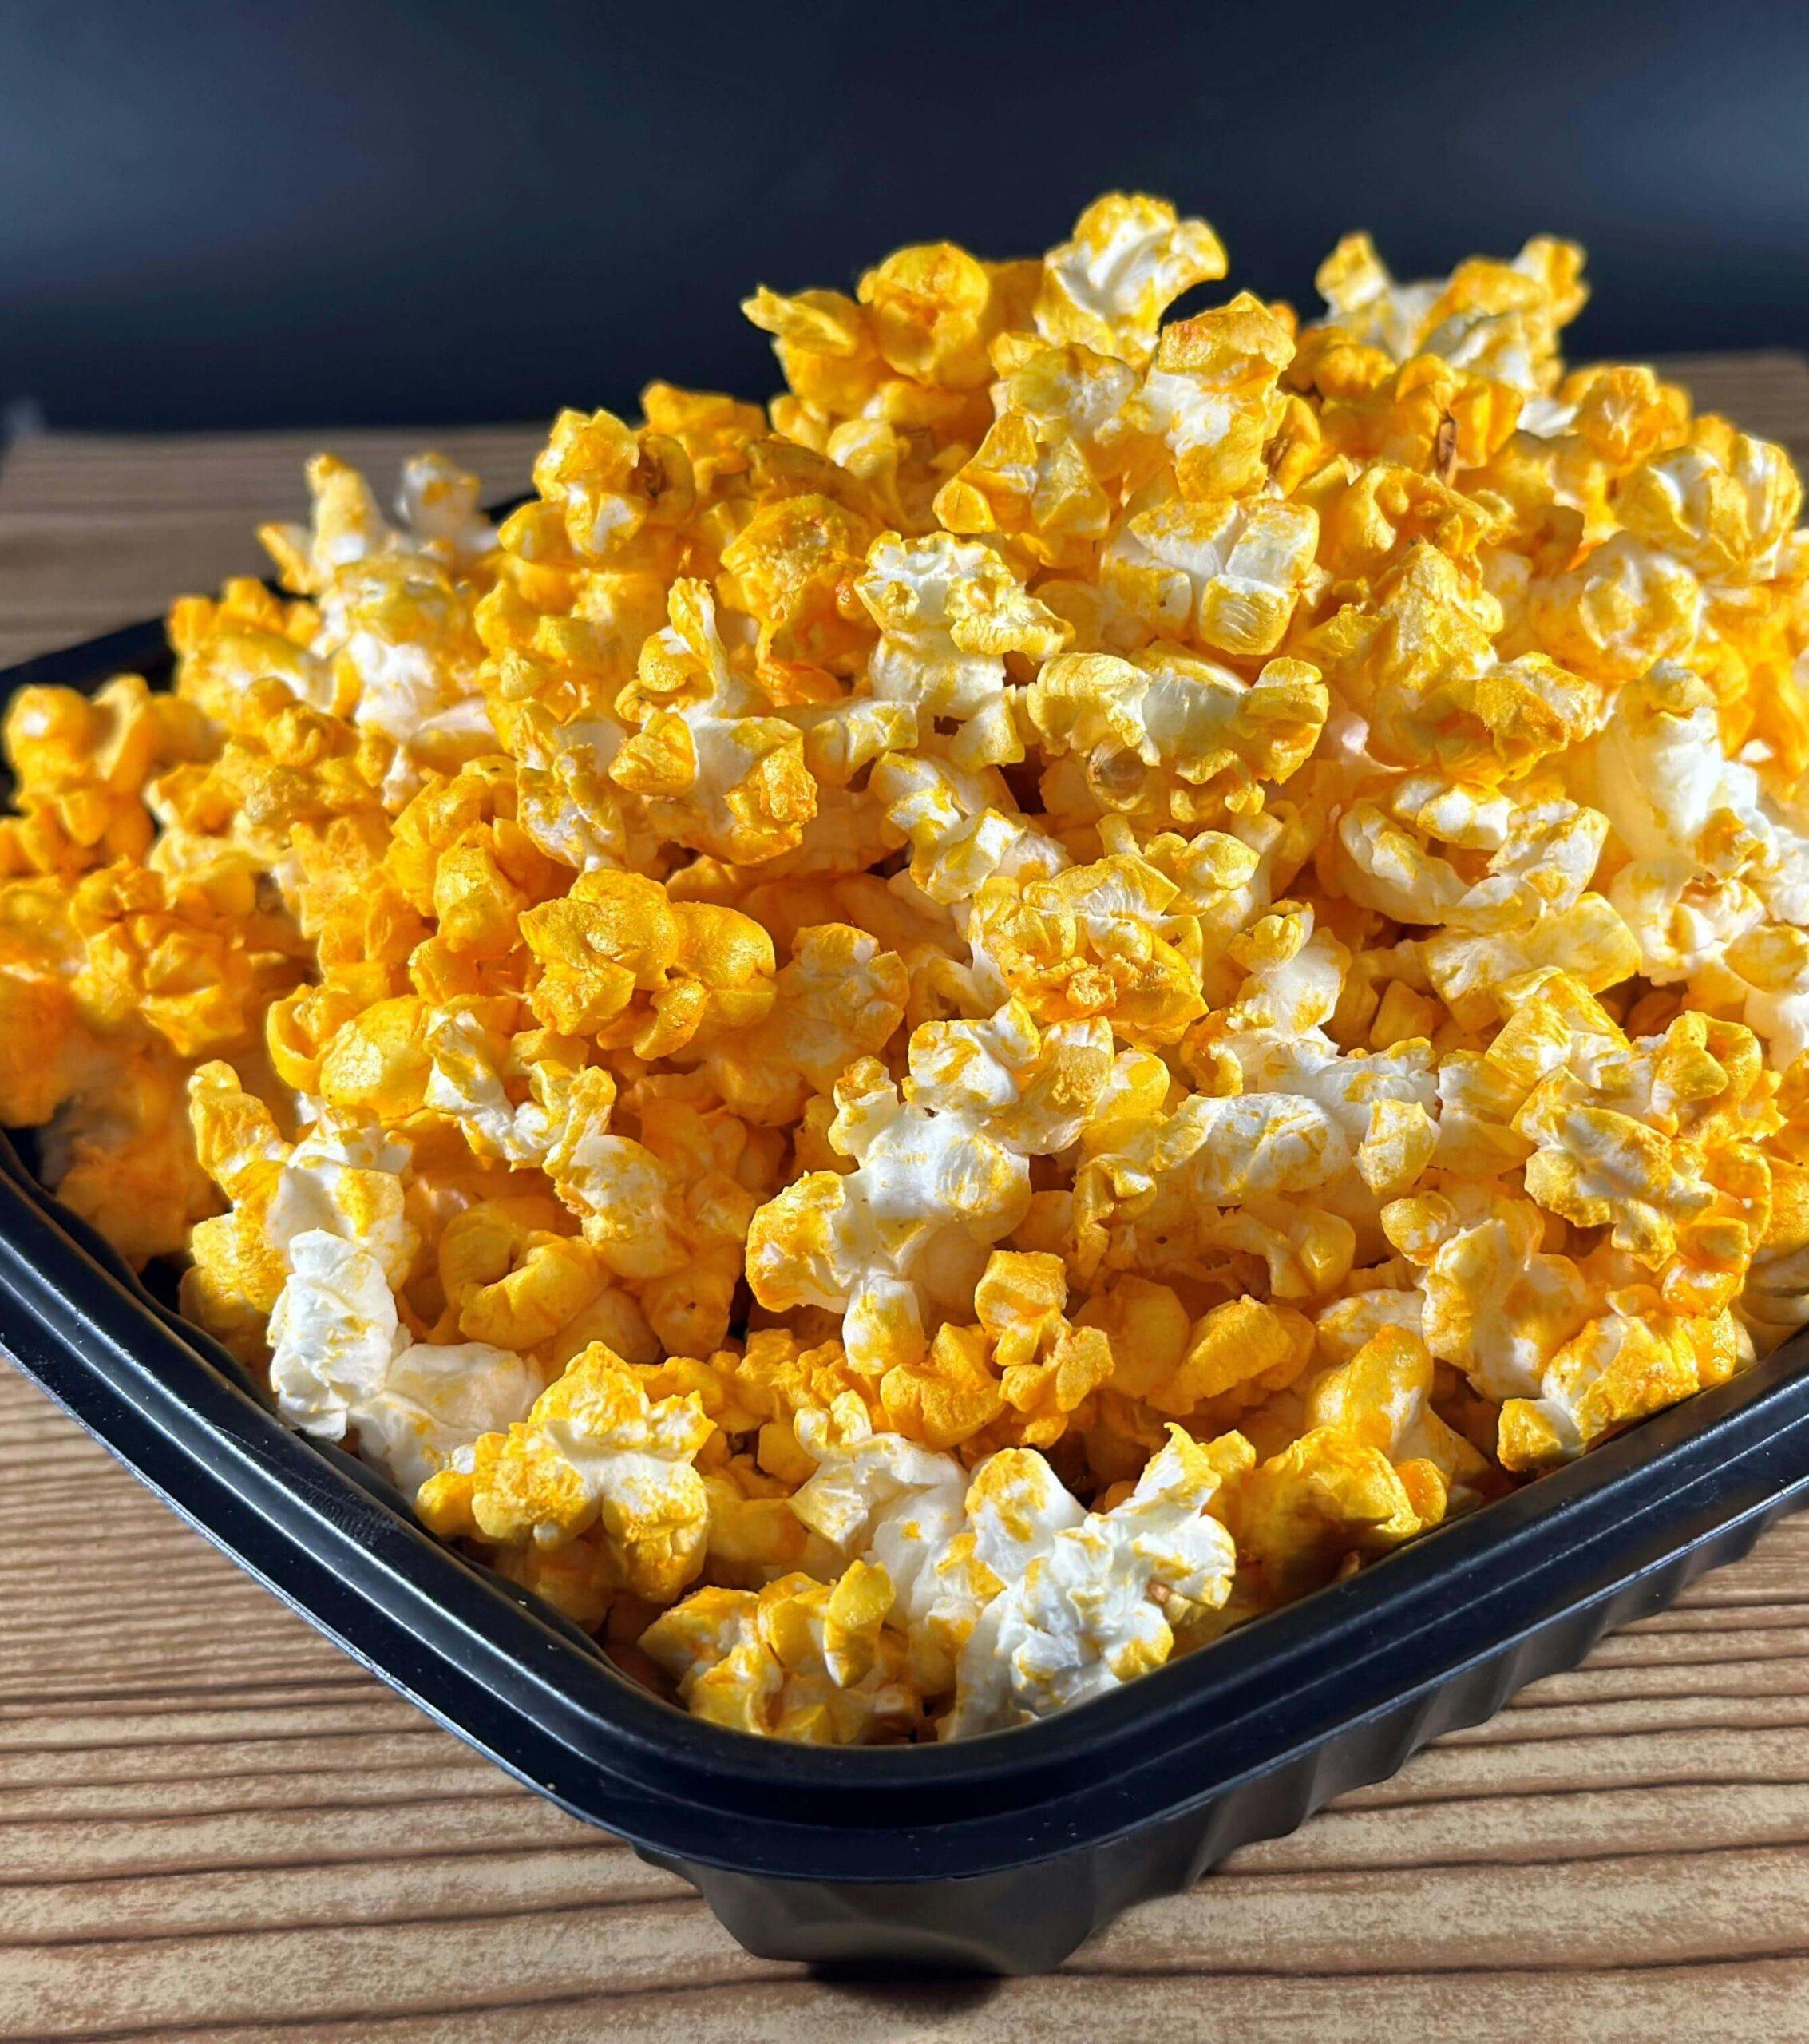
Cannabutter Infused Popcorn
A cozy, low-effort edible made with cannabutter and simple seasonings.
Prep Time 5 minutes mins
Cook Time 5 minutes mins
Total Time 10 minutes mins
Servings: 4 bowls
Course: Dessert, Snack
Cuisine: American
Ingredients
Method
- Pop the popcorn using your preferred method and transfer to a large mixing bowl.
- Melt the cannabutter (and regular butter, if using) gently over low heat until fully melted. Do not overheat.
- Slowly drizzle the melted butter over the popcorn while tossing to coat evenly.
- Add salt and any additional seasonings, tossing again to distribute.
- Portion into bowls and consume intentionally, starting with a small serving.
Notes
Dosing will vary depending on the potency of your cannabutter. Start with a small serving (2.5–5 mg THC) and wait at least 60–90 minutes before consuming more. Label clearly and keep out of reach of children and pets. For adults 21+ where cannabis is legal.
Why “Just Budget Better” Doesn’t Work When You’re Overwhelmed With Debt
Why "Just Budget Better" Doesn't Work When You're Overwhelmed With Debt
People love to say “just budget better” as if budgeting exists in a vacuum. As if the only thing standing between you and financial stability is a better spreadsheet or more discipline. When you’re overwhelmed, that advice doesn’t feel helpful. It feels dismissive.
When money stress is high, budgeting stops being a neutral tool for me. It turns into another reminder of everything that isn’t working. Every category feels too tight, every number feels off, and instead of clarity, I’m left feeling more pressure than before. That’s usually the moment people assume you need to try harder, when in reality, that’s the moment your capacity is already tapped out.
When money is tight, I don’t magically become more organized. I actually do the opposite. I avoid logging in. I delay decisions. I let things sit longer than I should because looking at them feels overwhelming. No app or budgeting method has ever fixed that response. If anything, strict budgeting makes it worse because it asks for structure at the exact moment I need flexibility.
What I’ve learned is that budgeting isn’t always the place to start. Sometimes it’s something you work back toward once things feel steadier. When I’m overwhelmed, trying to “budget better” just adds another layer of pressure. What helps more is simplifying the situation so I can stay engaged instead of shutting down.
That usually means stripping things down to the basics. Instead of a full budget, I look at a simple list of bills. Just what’s due and when. I don’t worry about categories or perfect allocations. I’m just trying to understand what I’m actually dealing with in real time. From there, I focus less on optimization and more on consequences. Which bills cause real problems if they’re late, and which ones have some flexibility? Are there due dates that can be moved to line up better with a paycheck? Sometimes a single phone call makes a month feel more manageable.
Overwhelm also changes how progress needs to be measured. When everything feels abstract, I lose motivation quickly. Looking at balances that barely move doesn’t encourage me to keep going. Tangible actions help more. Tracking small efforts, like selling items to put money toward debt, makes progress feel real even when it’s slow. That’s what keeps me showing up instead of avoiding everything.
I also don’t try to solve the entire picture at once. When money is tight, I decide what gets paid first and let the rest wait. I make one paycheck decision at a time and reassess as I go. That approach might not look impressive on paper, but it keeps me functional. And staying functional matters more than following a perfect plan I can’t maintain. I’ve written more about how I actually make those decisions when money is tight, because figuring out what gets paid first has mattered more for me than trying to follow a perfect budget.
A lot of budgeting advice ignores the reality of living in an economy where wages don’t match the cost of living, rent keeps increasing, groceries cost more every month, and extra income isn’t guaranteed. When the math doesn’t work, no amount of discipline fixes that. Pretending otherwise just turns systemic problems into personal failures.
I’ve had to unlearn the idea that struggling with budgeting means I’m irresponsible. I already carry enough shame around debt and where I “should” be by now. But shame has never helped me make better decisions. It’s only ever made me avoid them. Letting go of that has made it easier to approach my finances with honesty instead of fear.
Budgeting can still be useful. I’m not against it. I just don’t believe it works the same way in every season of life. When you’re overwhelmed, the goal isn’t control. It’s stability. It’s staying present enough to keep making decisions, even if they’re imperfect. Sometimes that means setting aside advice that sounds good and choosing what actually fits your reality. That’s why I focus more on deciding what debt gets paid first when money is tight instead of forcing a perfect budget.I’m not against budgeting. I just know that sometimes capacity has to come before structure. I’m still figuring out what works for me in different seasons, and I’ll keep sharing it as I go further in my High Debt series! Follow along!
How I Decide What Debt Gets Paid First When Money Is Tight
How I Decide What Debt Gets Paid First When Money Is Tight
When money is tight, deciding which debt to pay first can feel overwhelming and produce a huge mental load. Every bill feels urgent. Every balance feels loud. And somehow, no matter what you pay, it still feels like the wrong choice.
For a long time, I thought there was a perfect order. Some clean, strategic formula that would tell me exactly which debt deserved attention first. But when money is tight, the goal isn’t perfection. It’s stability. And stability looks different than optimization.
Before I decide which debt to pay first, I look at my actual life. Rent. Utilities. Groceries. Transportation. If paying a credit card means I’m stressed about basic living expenses two weeks later, that’s not responsible. That’s reactive. Debt never comes before keeping my life steady.
Once the essentials are covered, I stop thinking about balances and start thinking about consequences. Some debts are loud but flexible. Others move quickly toward fees, reporting, or escalation. When I can’t pay everything, I prioritize what could create immediate damage not what simply looks intimidating. That’s the exact framework I break down in my paycheck-to-debt decision planner.
I’ve also stopped obsessing over the size of a balance. A larger number doesn’t automatically make it the priority. What matters more is timing. What’s due before my next paycheck? What will add stress if it sits untouched? When money is tight, I care more about what keeps the next few weeks calm than what looks impressive on paper.
If I can’t pay something in full, I make a partial payment without turning it into a moral crisis. That took practice. For a long time, anything less than the full amount felt like failure. Now I see it differently. Paying what I realistically can is still participation. It keeps the account active. It keeps me engaged.
And when two payments feel equally important, I choose the one that lets me breathe after I click submit. That might not sound strategic, but it is. The payment that reduces mental noise is often the one that makes it easier to keep going.
I don’t try to solve my entire debt situation in one paycheck. I decide what keeps me stable now and let future paychecks handle future decisions. That approach has done more for my consistency than any strict budgeting system ever did.
Debt still exists. The numbers are still there. But the pressure feels lighter when I focus on maintaining stability instead of chasing the perfect order.
If you’re in a tight month, the “right” debt to pay first is the one that keeps your life functioning. The rest can follow. If budgeting still feels impossible right now, I’ve written about why “just budget better” doesn’t work when you’re overwhelmed with debt. You can check that out here!
My Paycheck Reset: How I Rebalance After a Bad Money Month
My Paycheck Reset: How I Rebalance After a Bad Money Month
Some months don’t just go a little off track. They fall apart. A bill hits earlier than expected, something unexpected comes up, or I’m already exhausted and make choices I wouldn’t have made in a calmer season. By the time the month ends, the damage feels done, and the pressure to “fix it” immediately kicks in.
I used to treat those months like failures. I’d promise myself I’d be stricter next time, more disciplined, more on top of things. That approach never worked. It only made the next month feel heavier before it even started. What’s helped more is having a reset that isn’t about erasing the past month, but about getting steady again without spiraling.
For me, a paycheck reset isn’t a fresh start. It’s a re-entry point. It’s how I move forward after a bad month without pretending it didn’t happen or punishing myself for it.
The first thing I do is shrink my focus. I don’t look at the entire month or the full debt picture. I look at the next paycheck only. What’s due before the next time I get paid? What absolutely needs to be covered so my life doesn’t get disrupted further? Keeping the scope small makes it easier to stay engaged instead of freezing.
Once I know what’s immediately due, I think in terms of timing and consequences rather than totals. I’m not trying to optimize or catch up all at once. I’m trying to prevent the situation from getting worse. That might mean letting some things wait, making partial payments, or choosing the option that buys me time. Resetting is about containment, not perfection.
I’m also careful not to overcorrect. After a bad month, it’s tempting to cut everything non-essential or try to make up for lost ground aggressively. That usually backfires for me. Extreme restrictions make me more likely to burn out and repeat the same patterns. Instead, I aim for balance. I tighten where I realistically can, but I don’t strip everything down to the point where the next few weeks feel unbearable.
Part of the reset is deciding what not to focus on right away. I don’t obsess over balances or replay every decision that led to the bad month. That information doesn’t help me move forward. What helps is getting back into the habit of making decisions at all. Once I’m doing that consistently, clarity comes back on its own.
This is also where prioritization matters. When money is tight after a rough month, I lean on the same approach I use to decide which debt gets paid first when money is tight, because making one clear decision matters more than trying to rebalance everything at once.
I’ve noticed that the reset is working when my relationship with my finances starts to feel calmer. I’m checking accounts without dread. I’m making decisions instead of avoiding them. I’m not fully caught up yet, but I feel steadier, and that matters more in the moment. Progress doesn’t always look like numbers moving dramatically. Sometimes it looks like staying engaged instead of giving up.
A bad month doesn’t mean I’m bad with money. It means I’m living in real life, where things don’t always line up neatly with a plan. The paycheck reset gives me a way to respond to that reality without adding shame or pressure. For me, rebalancing isn’t about starting over. It’s about getting stable enough to keep going, one paycheck at a time.
If you need a simple way to map out that next paycheck without overcorrecting, here’s the paycheck-to-debt decision planner I created and use to reset after a rough month.
How I’m Navigating Debt in a Broken Economy (With Accountability, Not Shame)
How I’m Navigating Debt in a Broken Economy (With Accountability, Not Shame)
I’ve been thinking a lot about what accountability actually means in a season where the economy feels broken. Not broken in a dramatic, headline way, but in a quiet, everyday way. The kind where you work full time, do what you’re “supposed” to do, and still end up living paycheck to paycheck.
For me, accountability no longer means doing everything perfectly. It means showing up even when I don’t want to. It means being honest about what I can and can’t sustain, and then committing to the choices I make instead of constantly backtracking.
A simple example: if I say I’m done using DoorDash, then I’m done. Not “mostly done.” Not “unless I’m tired.” If I give myself that boundary, I stick to it. That’s accountability for me right now. Not punishment. Not restriction. Just consistency.
What makes this season especially hard is that so much of the advice around debt assumes the economy is fair. It assumes wages match the cost of living. It assumes rent isn’t increasing faster than paychecks. It assumes groceries are manageable and that finding a part-time job to supplement income is realistic. None of that feels true right now.
I work full time. And still, things feel tight. That disconnect messes with your head. It makes you question yourself instead of the system. It turns financial stress into personal shame, even when the math doesn’t add up.
For a long time, I carried the belief that I shouldn’t have gotten myself into this debt. That if I were smarter or more disciplined, I wouldn’t be here. I have degrees. I’ve done the work. And yet, there isn’t a savings cushion that reflects any of that. That narrative is hard to shake. It’s easy to turn debt into a moral failure instead of what it often is: a combination of timing, systems, and survival.
That’s where the shame creeps in. And shame is what makes people avoid their finances altogether.
I’ve learned that strict budgeting doesn’t work for me when I’m already overwhelmed. Neither does pretending I can’t enjoy my life at all until every balance is gone. When I try to force myself into rigid systems, I don’t become more disciplined. I shut down. I avoid looking. I backtrack. That’s not accountability, it’s burnout.
What’s been more helpful is narrowing my focus. Instead of trying to fix everything at once, I make decisions that keep me engaged. I prioritize what needs to be handled first when money is tight, and I give myself permission to let the rest wait. I’ve written more about how I decide what debt gets paid first when money is tight, because that shift alone has helped me stop spiraling.
I’m also learning how to track progress without turning it into another source of stress. I don’t need constant reminders of how far I still have to go. I need proof that my effort counts, even when it’s small. That’s why tracking things like selling items to pay down debt has worked for me. It makes progress feel tangible, not abstract, and it helps me stay consistent instead of giving up when things feel slow.
Accountability, in this season, looks like showing up imperfectly. It looks like choosing systems that don’t punish me for being human. It looks like making progress wherever I can, even if it doesn’t fit into a clean spreadsheet or a viral money framework.
I’m not pretending this is easy. And I’m not pretending I have it all figured out. But I am choosing to stop layering shame on top of an already difficult reality. The economy can be broken without me being broken too.
I still believe in accountability. I just believe it should support your life, not shrink it.
If you need a place to start, I put together the paycheck-to-debt decision planner I’ve been using to sort what gets paid first when money feels tight. You can check it out here.
Dear Debbie by Freida McFadden Book Review
Dear Debbie by Freida McFadden Book Review
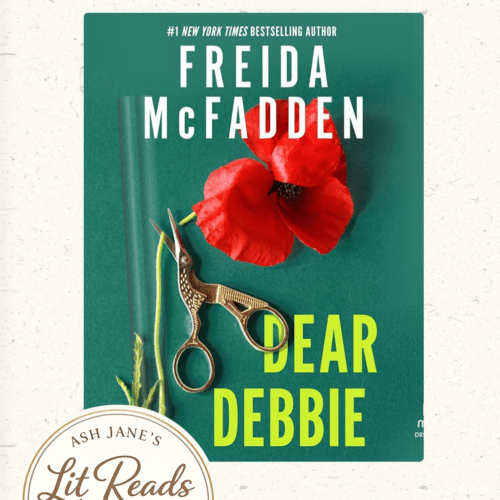
I’m not usually a dark-humor girl when I pick up a thriller. When I want thrills, I want thrills. No jokes unless it’s an ironic, “did that really just happen?” kind of laugh. So I was honestly surprised by how much I enjoyed Dear Debbie by Freida McFadden and the humor woven throughout the story.
My quick take: Dear Debbie is one of my favorite recent Freida McFadden reads, especially if you like fast thrillers, morally questionable women, dark humor, and a main character who has absolutely had enough. I gave it 4.9 out of 5 on my Lit Meter.
This isn’t laugh-out-loud comedy, but it is the kind of humor that makes you smirk or pause and shake your head. And somehow, it works. The balance between suspense and subtle humor felt intentional instead of distracting, which is not easy to pull off in a thriller.
At its core, Dear Debbie follows Debbie Mullen who seems like your typical suburban mom, she keeps the house running, raises her kids, and writes an advice column called Dear Debbie for her local paper, where woman after woman turns to her for sympathy, encouragement, and practical guidance. But when her own life starts to unravel , losing her job, family tensions rising, and secrets bubbling just beneath the surfaces, Debbie begins to question what being reasonable really gets her.
She’s always been someone who solves problems and not just for her readers, but for the people she cares about most. And when life starts pushing her to the edge, she doesn’t sit back and stay “reasonable” for long. Instead, she starts taking her own advice in ways that are surprising, unsettling… and sometimes downright ruthless. Debbie’s fierce loyalty to her family slowly reveals itself as a kind of warped justice: she’ll do anything for the people she loves, even if it means fighting fire with fire.
What I really liked was reading a thriller from the point of view of the person doing the dirty work. Debbie has a reason for everything she does. Whether you agree with her logic or not is another story, but she’s convinced she’s justified, and that makes the experience way more engaging. You’re constantly questioning whether she’s right, wrong, or somewhere in between.
The premise also hit a nostalgic note for me. I was obsessed with Dear Abby growing up and genuinely believed I could be the kid version of her. I even wrote in once with that dream in mind. Spoiler alert: she never responded. So when I saw the concept behind this book, I knew I had to read it as soon as it came out.
It’s no secret that I love Freida McFadden’s books. If you’ve read my review of The Boyfriend, you already know she’s one of my go-to authors when I want something fast, twisty, and bingeable. Dear Debbie absolutely delivered on that front. The twists were satisfying, and even though I’m starting to recognize some of her patterns, I still enjoy the ride every single time.
I finished this in about a day and a half. The only reason it took that long is because I had to work. Otherwise, this easily could’ve been a one-sitting read.
🔥 Lit Meter: 4.9/5 Lighters
Readability When High:
Very easy to follow and quick to get through. The chapters move fast, the perspective stays clear, and nothing feels overly complicated. This is a true binge read, even if you’re only half paying attention at first.
Mind-Blown Factor:
The twists aren’t jaw-dropping, but they’re satisfying. Once you start to understand Debbie’s mindset and motivations, things begin to fall into place. The fun is less about shock and more about watching how far she’s willing to go.
Vibe Check:
Everyday mom life, small-town routine, and quiet frustration simmering under the surface. It feels grounded and familiar, which makes the darker choices and humor hit harder as the story unfolds.
Smokability:
A smooth hybrid vibe. Relaxing enough to stay comfortable, but engaging enough that you don’t zone out. This is a “one more chapter” kind of read.
Would I Reread While Baked?:
Yes. This feels like a good reread because knowing Debbie’s motivations adds another layer to her decisions. The buildup and internal logic are just as entertaining the second time around.
If you enjoy thrillers that are quick, a little messy, and told from an unexpected point of view, Dear Debbie is worth picking up. It’s not heavy or emotionally draining, but it is entertaining and easy to get lost in. You can grab your copy here and see for yourself why this one kept me hooked until the very last page.
Not sure if this one is for you? Take the quiz below and find out what you should actually be reading right now!
🍃 High on Books
What Should You Read Next?
Answer a few questions and we'll match you with your perfect next read.
Question 1 of 7
0%
Question 1
Your vibe is...
Ashley Jane's Picks for You
Copied to clipboard! 📋
